Navigating The Home Market Before 2026 Ends
Blogs20 Nov 202610 min read

Singapore’s private home price index rose 1.4% in Q3 2026, the fastest quarterly pace in almost two years, even as total private transaction volume which consist of new sale, sub sale and resale fell to its lowest level since Q1 2024. Behind the quiet quarter, developers have been paying record prices for land, which will shape what new launches cost in 2027. In this article, we take a closer look at what the Q3 numbers are telling us and follow the land bids to the next chapter for home buyers.
2026 Policy Changes Point to a More Sustainable Market
The government has been fine-tuning housing policy throughout this year, and every calibration points toward a more sustainable market. The changes that matter most for buyers are the removal of the 15-month wait-out period for private owners buying HDB resale flats, higher income ceilings for Build-to-Order (BTO) flats and executive condominiums (EC), and greater priority for families with children.
Table 1: Housing Policy Changes Announced in 2026
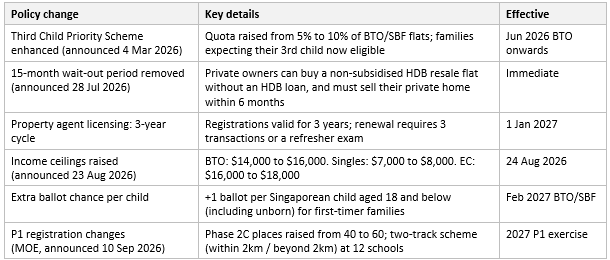
The Primary 1 registration changes are also worth watching, as they could shift demand for some homes near popular schools.
Private Prices Rose in a Quiet Quarter, Even As Volumes Fell
The All-Residential Property Price Index reached 222.5 in Q3 2026, up 1.4% q-o-q and 2.8% for the first nine months of 2026. Non-landed prices rose 0.9% q-o-q, led by the OCR at 2.2%, while the RCR edged up 0.2% and the CCR slipped 0.1%. Landed prices climbed 2.8%.
Transaction volume told a different story. About 4,700 caveats were lodged in Q3 2026, down from 6,148 in Q2 and about 36% below the 7,404 in Q3 2025. The likely reason is seasonal. Q3 2026 included the Lunar Seventh Month, when developers typically delay launches. Therefore, there were only three major launches in Q3: Lentor Garden Residences (District 26, OCR), Dunearn House (District 10, CCR) and Amberwood at Holland (District 10, CCR).
Chart 1: All-Residential Property Price Index and Total Private Transactions, Q1 2021 to Q3 2026
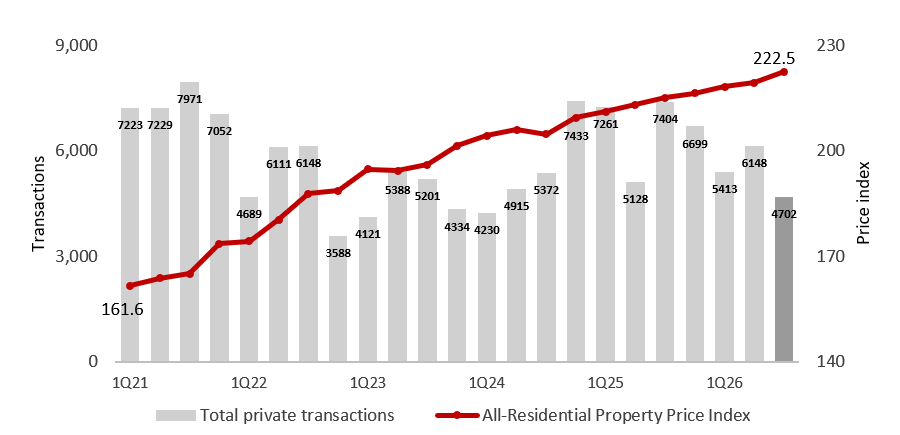
Despite fewer transactions, prices held firm, which indicates that buyers were selective but still willing to buy when they saw value.
Well-Located Projects at the Right Price Continue to Sell
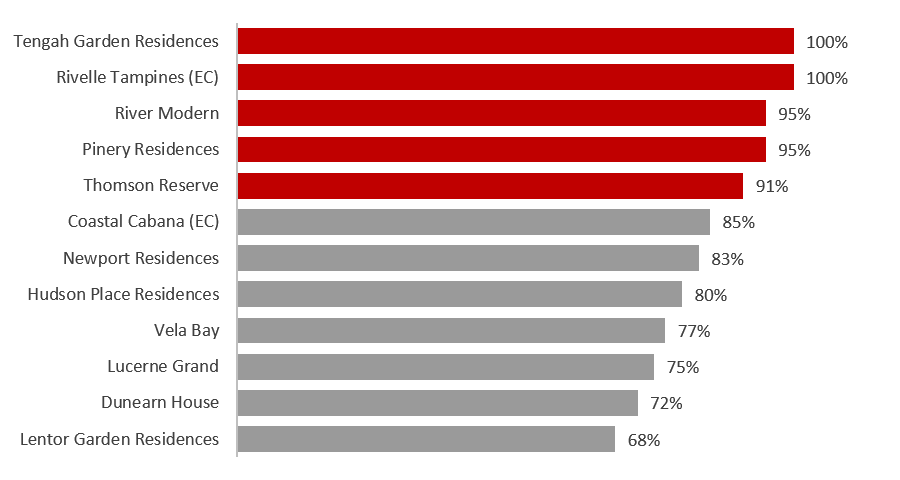
Take-up across this year’s launches shows a clear pattern. Tengah Garden Residences and Rivelle Tampines (EC) are fully sold, while River Modern (95%), Pinery Residences (95%) and Thomson Reserve (91%) are not far behind. Coastal Cabana (EC), Newport Residences and Hudson Place Residences are between 80% and 85% sold, followed by Vela Bay (77%), Dunearn House (72%), Lucerne Grand (75%) and Lentor Gardens Residences (68%).
Chart 2: Take-up Rate of 2026 New Launches
The Price Gap Between New and Resale Condos is Narrowing
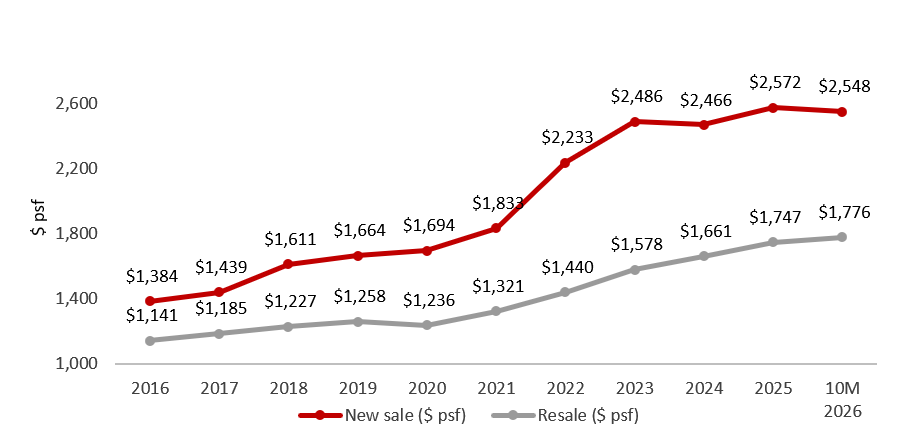
One reason new launches remain in demand is the narrowing premium over resale condos. The gap between median new sale and resale prices peaked at $908 psf in 2023 and has since narrowed to about $772 psf in 2026.
The narrowing price gap is due to strong resale price growth. Since 2023, the median resale price rose 12.5% to $1,776 psf, while the median new sale price rose only 2.5% to $2,548 psf, narrowing the new sale premium from about 58% to about 44%. For many buyers, paying a little more for a brand-new home with modern layouts, full facilities and a longer lease could look like a better deal than a resale unit.
Chart 3: Median New Sale and Resale Condominium Prices, 2016 to October 2026
HDB Resale Volumes Rose After the Wait-Out Removal
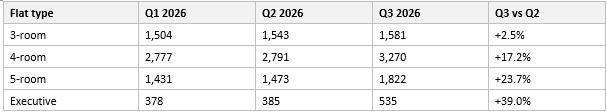
The removal of the 15-month wait-out period on 28 July helped lift HDB resale activity in Q3. Resale transaction volume rose 17.7% q-o-q to about 7,500, but the HDB Resale Price Index dipped 0.2% to 202.5, the third consecutive quarterly decline.
The increase in demand came from larger flats. Compared to Q2, 4-room sales rose by 17.2%, 5-room sales increased by 23.7% and executive flats jumped 39.0%, which is consistent with more private homeowners right-sizing into HDB after the removal of the 15-month wait period.
Table 2: Resale HDB Transactions by Flat Type, Q1 2026 To Q3 2026
Million-Dollar HDB Flats Hit a Record High
A record 597 HDB flats were sold for $1 million or more in Q3 2026, marking the first time that the number crossed 500 in a quarter. In addition, this is up 21.8% from 490 in Q2.
Most of these million-dollar deals are in mature estates, accounting for 519 of the 597 transactions. This was led by Toa Payoh with 93 deals, followed by Queenstown with 86 and Bukit Merah with 56.
Chart 4: Million-Dollar HDB Flat Transactions, Q2 2023 to Q3 2026
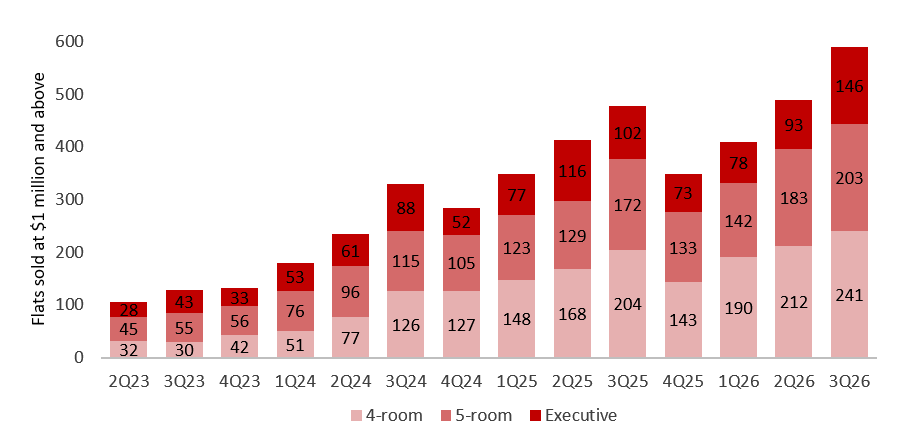
This is part of the property cycle: sellers profit from price growth, upgraders have more funds for their next home, and retirees can right-size. However, million-dollar flats are still only about 8% of resale deals, indicating that most flats remain affordable.
Buyers Have Real Money Behind Them
With prices higher today, three groups of buyers stand out.
- HDB upgraders. Many have sold their HDB flats for a profit, so they have more funds for their next home.
- Right-sizers. Older owners are selling larger homes, purchasing smaller ones and keeping the surplus for their retirement.
- Financial help from parents. More parents are financially helping their children to purchase their first home or move up the property ladder.
Land Prices are Up in Every Region, and Launch Prices are Expected to Follow
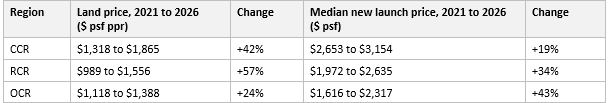
A closer look at land prices shows increases in all three regions over the past four years: about 42% in the CCR, 57% in the RCR and 24% in the OCR. Land prices are a good indicator of future new launch prices.
In the CCR and RCR, median new sale prices have climbed at a slower pace than land, increasing 19% and 34% respectively. In contrast, median OCR launch prices have already risen 43%, ahead of the 24% increase in land prices.
Table 3: Land Price and Median New Launch Price by Region
Developers are still paying top dollar for residential sites. Three recent government land sales stand out:
- Berlayar Drive (near Keppel Bay) was awarded in August 2026 for $1,515 psf ppr.
- New Upper Changi Road (Bedok) was awarded in September 2026 for $1,537 psf ppr, which was a new record-high for the OCR.
- Lorong Puntong / Sin Ming Avenue was awarded in September 2026 for $1,612 psf ppr, which was a new record-high for the RCR.
These bids signal that developers are confident about the long term prospects for Singapore’s residential property market.
ECs: Land Prices have More Than Doubled Since 2017
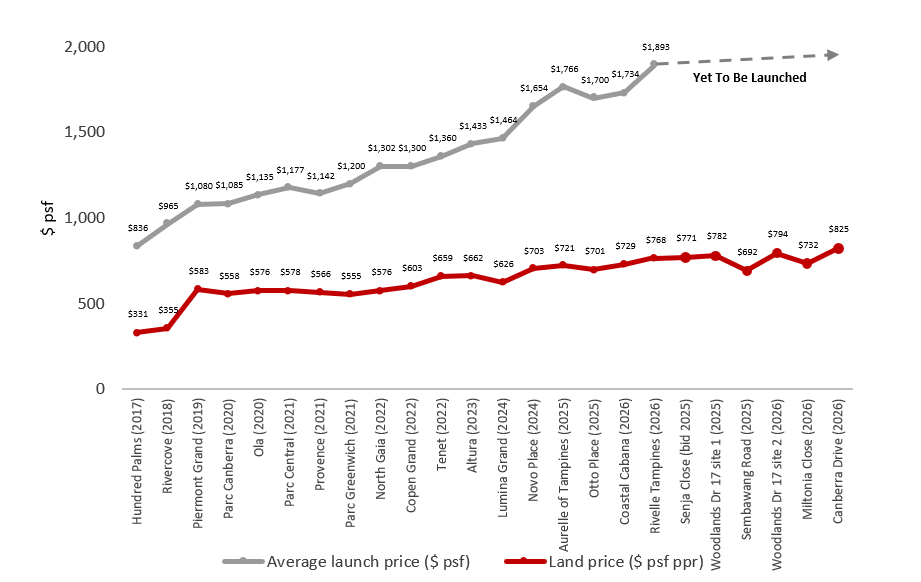
EC land prices have climbed steadily. In 2017, the developer paid $331 psf ppr for the land and launched Hundred Palms Residences at $836 psf. This year, the developer paid $768 psf ppr for the land and launched Rivelle Tampines at $1,893 psf.
Chart 5: EC land price and average launch price, in order of launch or land bid, 2017 to 2026
The Price Gap Between New ECs and New OCR Condos is Shrinking
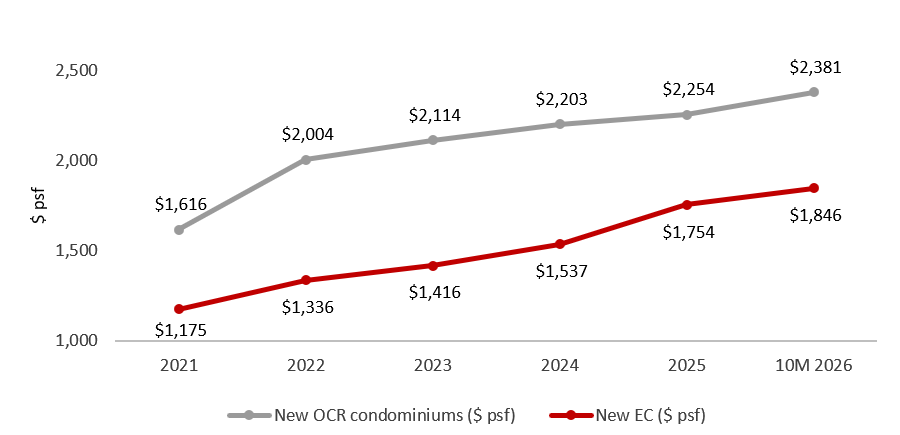
New ECs used to be significantly cheaper than new OCR condominiums. The gap between OCR new launch average prices was $698 psf in 2023, but has narrowed to $535 psf in the first 10 months of 2026, with new ECs at $1,846 psf against $2,381 psf for new OCR condos.
This matters because ECs now come with tighter rules: a 10-year MOP and no Deferred Payment Scheme. A new OCR condo may cost only a little more but carries none of the EC restrictions, so EC buyers should be clear about what they prioritise.
Chart 6: Average launch price of new ECs and new OCR condominiums, 2021 to 10M 2026
Despite the new regulations, developers remain confident about the EC market, as evident by the Canberra Drive GLS site, which is the first EC site subjected to the new rules. The tender closed on 1 October and was awarded on 15 October. The winning bid was $163.9 million, or $825 psf ppr, which is the highest ever for an EC site. The site is within a 10-minute walk of Canberra MRT Station, Canberra Plaza and Sembawang Shopping Centre. Schools within a 1km radius include Sembawang Primary School, Wellington Primary School and Ahmad Ibrahim Secondary School. The tender result offers three signals:
- 13 bidders is a strong turnout, indicating developers are optimistic about ECs despite the regulatory changes.
- Bids ranged widely, from $361 to $825 psf ppr, so views on the EC market do differ.
- Six bids exceeded $700 psf ppr, which suggests that most developers remain optimistic.
Not Every Upcoming EC Is Affected By The New Rules
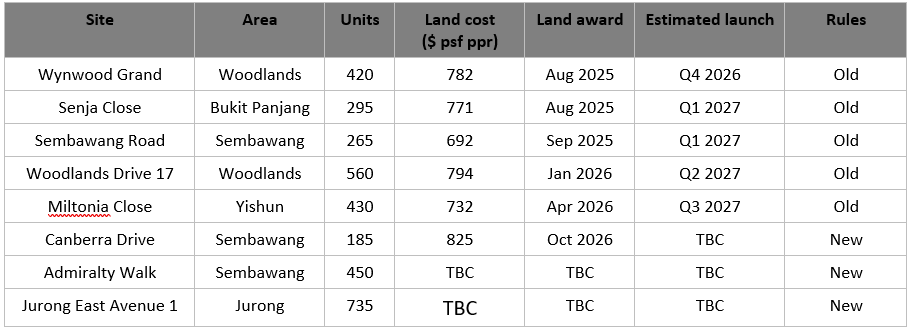
Sites sold before 8 May 2026 follow the old rules, which makes the first five projects in Table 4 possibly buyers’ last chance to buy an EC under them. Sites sold after that date follow the new rules: a 10-year MOP, no Deferred Payment Scheme, a 2-year wait-out for second-timers and a 90% first-timer quota.
Table 4: Upcoming EC Sites And The Rules That Apply
Planning Your Move Before 2026 Ends
First-Time Buyers: Is Now The Time For BTO?
More families can now consider a BTO. The income ceiling rose from $14,000 to $16,000 (singles: $8,000), which will benefit households whose income was just above the old limit. Families with children also get an extra ballot chance from the February 2027 exercise, and grants of up to $120,000 keep BTO the most affordable path to homeownership.
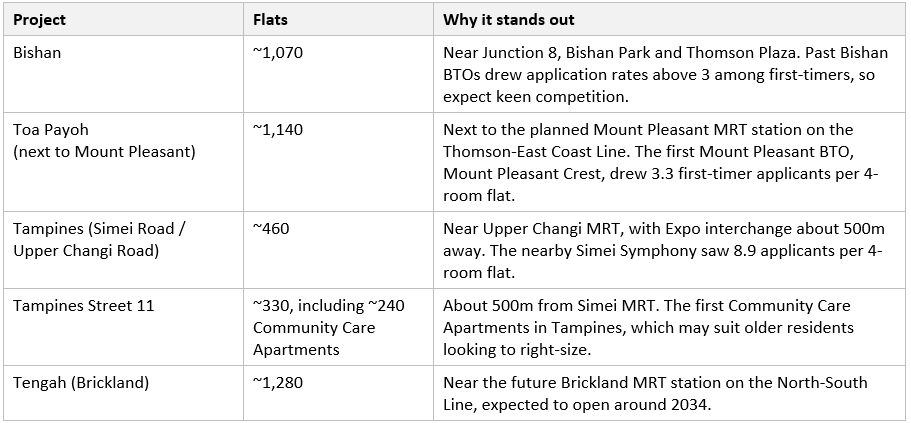
The timing is good. The February 2027 exercise offers about 4,300 BTO flats across five projects in Bishan, Toa Payoh, Tampines and Tengah, alongside about 5,000 Sale of Balance Flats.
Table 5: Projects To Look Out For In The February 2027 BTO Exercise
Popular central BTOs could also draw some buyers away from the resale market, especially those who can wait for a new flat. Your first property does not have to be your dream home. It simply needs to be the right first step.
Upgraders And EC Buyers
The five remaining EC sites that are subjected to the old rules (Table 4) are likely the last chance to buy an EC without the 10-year MOP and with deferred payment. The first, Wynwood Grand in Woodlands, will preview in 4Q 2026 and officially launch in 1Q 2027.
In 1H 2027, 7 OCR condominiums with a combined total of about 4,069 units are expected to launch. Buyers who prefer the flexibility of a private condo might want to consider these projects.
The Master Plan Should Guide Investors
Investors should take their cue from the Master Plan. Areas undergoing transformation tend to reward patient buyers, and three areas are worth watching: Jurong Lake District (Singapore’s second CBD), Health City Novena and Thomson-Bishan. Better connectivity will also add to their appeal, thanks to the Jurong Region Line, Cross Island Line, Thomson-East Coast Line and North-South Corridor.
Having been through many property cycles, one lesson stands out: waiting also has a cost.