3Q 2026 Landed Report: Landed Prices Rise 2.9% in 3Q 2026 Even as Transaction Volumes Eased
Research11 Nov 20268 min read

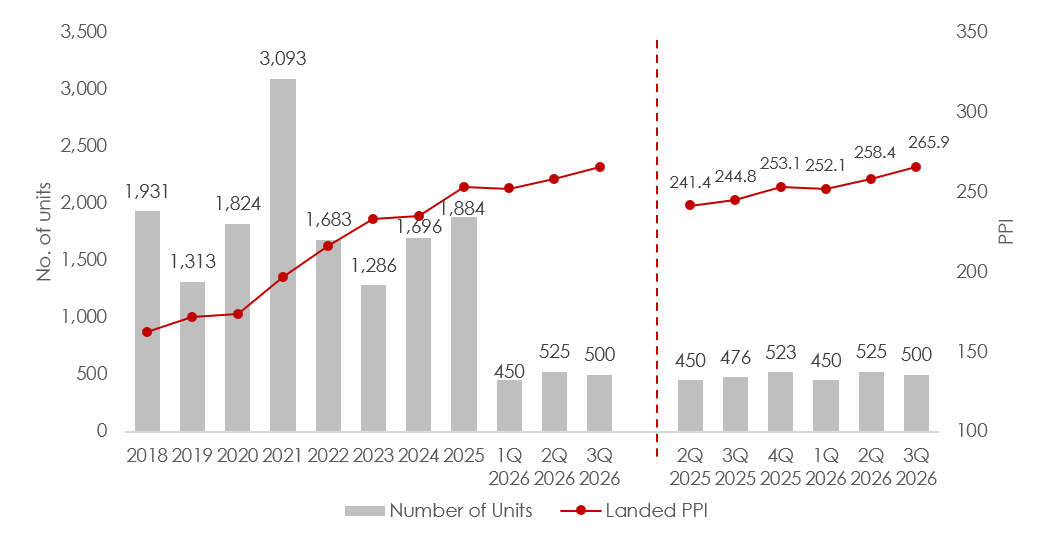
Landed home prices continued to rise in 3Q 2026, with the landed price index increasing 2.9% q-o-q, from 258.4 in 2Q 2026 to 265.9. The increase was faster than the 2.5% rise in 2Q 2026 and marked a second consecutive quarter of growth, following a 0.4% dip in 1Q 2026. Landed homes again outpaced non-landed private homes, which rose 1.0% q-o-q.
The annual increase in the price index for landed homes is more pronounced. The index rose 8.6% y-o-y, from 244.8 in 3Q 2025 to 265.9 in 3Q 2026. Year to date, landed prices have risen 5.1% from 253.1 in 4Q 2025, putting them within ERA's full-year forecast of 5% to 7%.
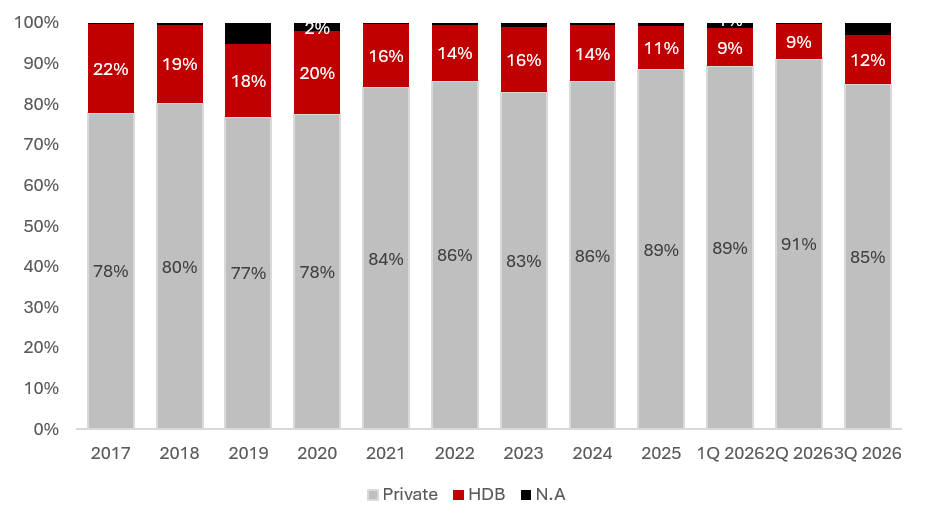
However, fewer landed homes changed hands this quarter, while the median price remained steady at $5.39 million. This suggests that the lower transaction volume may reflect a mismatch in price expectations: sellers held firm, while buyers who proceeded were willing to pay more for these scarce assets. HDB upgraders also returned in greater numbers, accounting for 12% of landed home buyers, up from 9% in 2Q 2026.
Landed Property Price Index and Transactions
Based on URA caveats, there were 500 landed transactions in 3Q 2026, down 4.8% quarter on quarter from 525 in 2Q 2026, but up 5.0% year on year from 476 in 3Q 2025.
Momentum eased as the quarter progressed, with monthly transactions falling from 192 in July to 154 in both August and September. Despite lower volume in 3Q 2026, the 1,475 landed transactions recorded during the first nine months of 2026 were 8.4% higher than the 1,361 recorded in the same period in 2025.
Chart 1: Landed Property Price Index and Transactions
Price Quantum
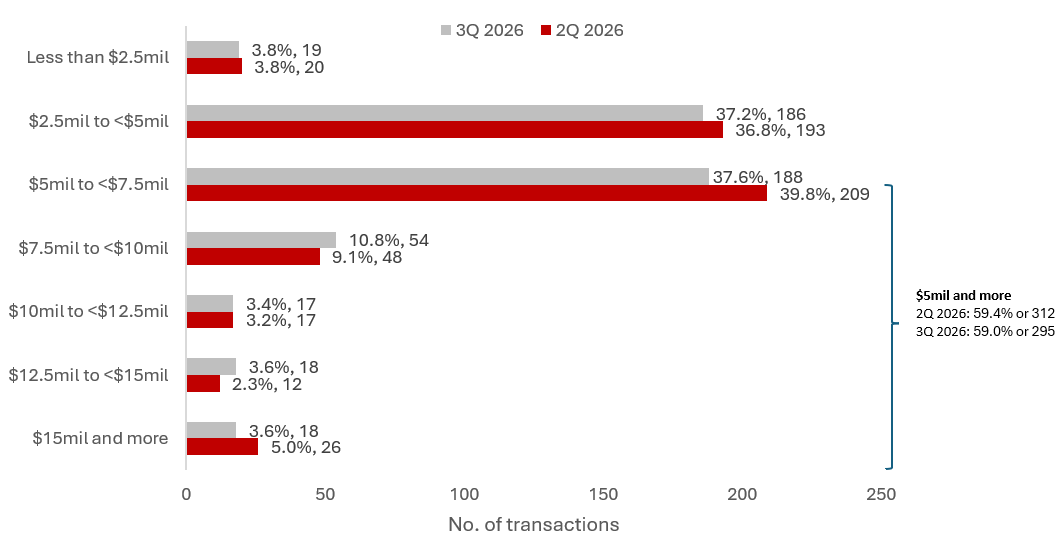
The share of landed homes sold for at least $5 million remained steady in 3Q 2026. These transactions accounted for 59.0% of sales, compared with 59.4% in the previous quarter. In absolute terms, 295 units were sold, down from 312. The median price quantum was largely unchanged at $5.39 million, versus $5.40 million in 2Q 2026, and was 5.8% higher than the $5.09 million recorded in 3Q 2025.
By proportion, the price distribution of landed home transactions remained broadly similar, with a slight shift towards the upper-middle range. Homes priced between $7.5 million and $10 million increased from 48 to 54 units, raising their share from 9.1% to 10.8%. Transactions in the $12.5 million to $15 million range also rose, from 12 to 18 units.
By contrast, transactions in the $5 million to $7.5 million range declined from 209 to 188 units, falling from 39.8% to 37.6% of all deals. Transactions at $15 million and above also fell, from 26 to 18 units.
This quarter, homes priced below $5 million accounted for 205 transactions, or 41.0% of the total, compared with 213 transactions, or 40.6%, in the second quarter.
Volumes in the $2.5 million to $5 million range dipped slightly, from 193 to 186 units, while volumes below $2.5 million remained nearly steady at 19 units, compared with 20 in the previous quarter.
Chart 2: Landed Price Quantum 3Q 2026 versus 2Q 2026
Strata-landed homes are another option for buyers. Located within a condominium development, these landed houses combine the privacy of a landed home with shared facilities such as a pool, gym and security. Transactions increased from 67 in 2Q 2026 to 97 in 3Q 2026, while the median price rose from $3.19 million to $3.65 million, partly driven by new sales.
The September relaunch of Belgravia Ace was well received. Eight units at the freehold strata-landed project on Belgravia Drive in District 28 were sold between 16 and 19 September, with prices ranging from $5.28 million to $5.70 million. Since the project has obtained its Temporary Occupation Permit (TOP), buyers can move into their new homes immediately, which may have boosted sales.
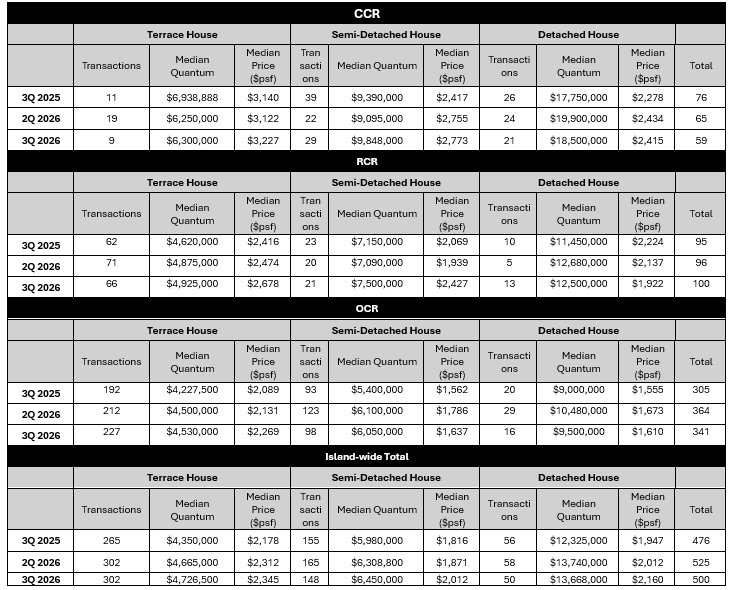
Sales performance varied across the landed housing sub-markets. Volumes declined 9.2% q-o-q in the CCR and 6.3% q-o-q in the OCR, while the RCR was the only sub-market to post growth, with transactions up 4.2% q-o-q. Notably, median price quantum increased for terrace houses across all three sub-markets and for semi-detached houses in the CCR and RCR, suggesting that lower volumes were not accompanied by lower prices.
By housing type, terrace house transactions were unchanged at 302 units, while semi-detached and detached house transactions fell 10.3% and 13.8% q-o-q, respectively.
Detached homes saw the sharpest decline in transactions, falling from 58 to 50 units. Their median quantum remained steady at $13.67 million, compared with $13.74 million in 2Q 2026, while median unit prices rose from $2,012 psf to $2,160 psf. The quarter’s largest landed transaction was a detached house on Dalvey Road in District 10, which sold for $56.0 million.
Transactions for Core Central Region (CCR) landed homes eased after a strong 2Q 2026, with 59 deals this quarter, down from 65 in 2Q 2026 and 76 in 3Q 2025. The 22.4% year-on-year decline was the steepest among the three sub-markets.
Median price for detached homes in the CCR eased from $19.90 million to $18.50 million, but median unit prices remained largely flat at $2,415 psf.
By contrast, the median quantum for CCR semi-detached homes rose from $9.10 million to $9.85 million. With fewer prime landed homes changing hands, buyers may face greater competition for these sought-after assets.
The Rest of Central Region (RCR) was the bright spot this quarter. Transactions increased to 100 units, up from 96 in 2Q 2026 and 95 in 3Q 2025, making it the only sub-market to record growth both q-o-q and y-o-y.
The median price of RCR semi-detached homes rose from $7.09 million to $7.50 million, while unit prices increased from $1,939 psf to $2,427 psf. RCR terrace houses also recorded higher prices, with median unit prices climbing from $2,474 psf to $2,678 psf. However, these figures are based on a small number of transactions, so they may not signal a rebound for these homes and should be treated with caution.
Most landed homes transacted were terrace and semi-detached houses in the Outside Central Region (OCR), with median prices of $4.53 million and $6.05 million, respectively. OCR transactions fell 6.3% q-o-q to 341 units, mainly because semi-detached deals declined from 123 to 98 units. The median price per square foot for OCR semi-detached homes also fell, from $1,786 to $1,637.
Despite this, OCR volumes were 11.8% higher than a year earlier. Landed homes in the OCR remain the most accessible entry point into this market segment, while new launches such as Luxus Hills and Pollen Collection II in District 28 expanded buyers' choices this quarter.
The landed price index rose 2.9% q-o-q in 3Q 2026, from 258.4 to 265.9, outpacing the 1.0% increase in non-landed private home prices. Within the non-landed segment, OCR prices climbed 2.3% q-o-q. This could support the next wave of upgraders: as suburban condo owners see their home values rise, they may be able to put more towards purchasing a landed OCR home.
For buyers, OCR semi-detached homes could offer an attractive opportunity in the coming quarters. Median unit prices fell from $1,786 psf in 2Q 2026 to $1,637 psf in 3Q 2026, while transactions declined from 123 to 98 units. Buyers in this segment may find more sellers willing to negotiate.
Table 1: Transaction Volume and Median Price by Landed Property Type and Market Segment
Purchasers Address Indicator
After declining for two consecutive quarters, the share of HDB upgraders buying landed homes rose in 3Q 2026. HDB addresses accounted for 12% of landed home buyers, up from 9% in 2Q 2026 and above the 11% recorded in 2025. Correspondingly, private address holders made up 85% of buyers, down from 91% in the previous quarter.
Chart 3: Landed home buyer profile
In conclusion
Landed home prices continued to climb in 3Q 2026: the price index rose 2.9% q-o-q, from 258.4 to 265.9, while transactions eased 4.8% q-o-q to 500 units. Sellers remained firm on price, with the median price quantum holding steady at $5.39 million.
Transaction performance varied across the sub-markets. The RCR was the only sub-market to see an increase in transactions, while volumes in the CCR and OCR declined.
The return of HDB upgraders is a positive sign for demand. Their share of landed home buyers climbed to 12%, its highest level since the start of 2025. Higher condo prices in the OCR may also give more condo owners enough equity to upgrade to a landed home.
With 1,475 transactions in the first nine months of 2026, the market is on track to meet ERA's forecast of 1,750 to 1,950 transactions. It could reach the upper end of that range if fourth-quarter 2026 volumes match the 523 deals recorded in fourth-quarter 2025. Prices are already up 5.1% year to date, keeping ERA's forecast of 5% to 7% price growth for 2026 firmly in view.