3Q 2026 Rental Report: Private Residential Rents and Activity Pick Up Alongside Growing Housing Completions
Research4 Nov 20265 min read

Private Residential Rental Market
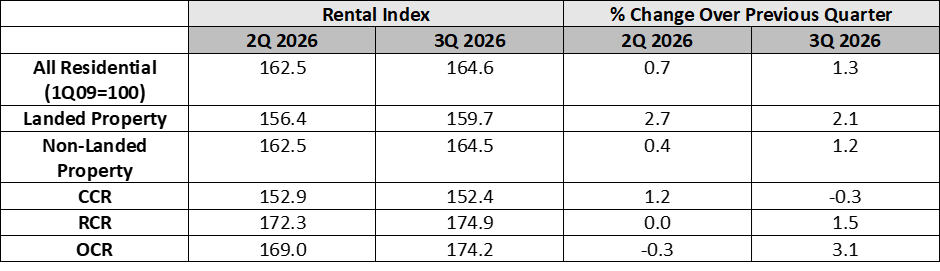
In the third quarter of 2026, Singapore’s private residential rental market, including Executive Condominiums (EC), saw sizeable increases in both rents and leasing activity. The all-residential rental index for private properties went up by 1.3% quarter-on-quarter (q-o-q) to 164.6, thus extending the 0.7% q-o-q growth recorded for 2Q 2026. This also marks the index’s sharpest quarterly uptick so far this year. On an annual basis, private residential rents have risen 1.8% compared with the same period last year.
Table 1: Comparison of Private Property Rental Index for 2Q 2026 and 3Q 2026
Leasing activity for all private properties and ECs rose in 3Q 2026, with a sizeable 25.3% increase on the quarter from 23,273 contracts to 29,154 contracts. On the year, rental activity grew by 4.6% compared to the 27,881 contracts in 3Q 2025. This also brought the total number of rental contracts inked in 9M 2026 to 74,220 cases.
Chart 1: Rental Contracts Across Landed, Non-Landed Private Properties and Executive Condominiums (Year and Quarter)
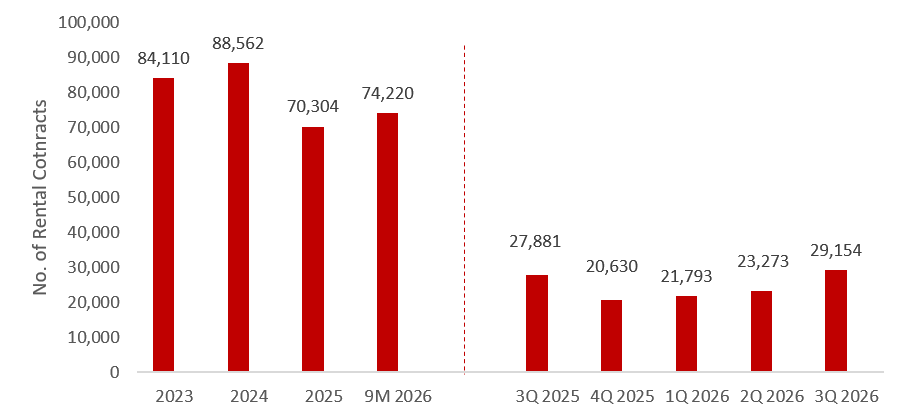
Chart 2: Rental Index of Non-Landed Private Properties (By Region) and Landed Properties
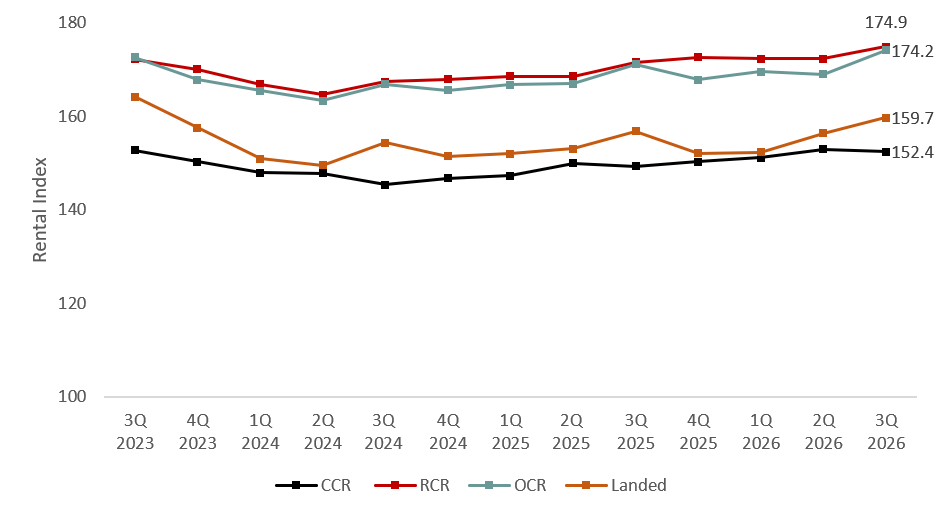
On a quarterly basis, the CCR was the sole segment that saw rents decline, with its rental index for non-landed private homes (excluding ECs) slipping by 0.3% q-o-q. In contrast, the OCR saw the strongest quarterly growth with a 3.1% q-o-q uptick in rents for corresponding properties. This was followed by the landed and RCR segments, which saw rents growing by 2.1% q-o-q and 1.5% q-o-q respectively.
Chart 3: Private Residential and EC Completions and Expected Pipeline Supply
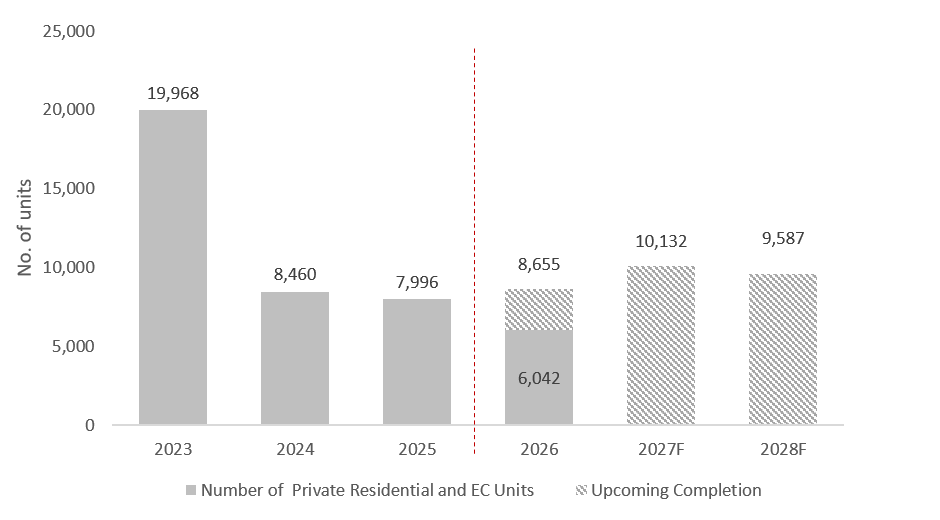
Mirroring the sharper growth in rents, private residential completions (including ECs) likewise rose sharply in the quarter to 3,559 units. This represents a 193.6% q-o-q increase from the 1,212 units completed in 2Q 2026, marking the highest quarterly total since 3Q 2024, when 3,953 units were completed.
Table 3: Notable Private Residential and EC Projects Completed in 3Q 2026
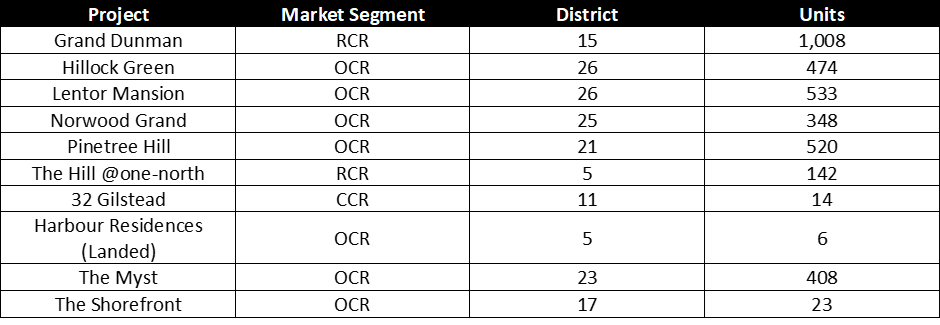
Notable private residential projects that obtained their Temporary Occupation Permit in 3Q 2026, include Grand Dunman, Hillock Green, Lentor Mansion, Norwood Grand, Pinetree Hill, The Hill @one-north, and The Myst.
Completions at these projects also contributed to a 0.8% q-o-q increase in the islandwide stock of completed private residential homes, which rose from 424,581 to 428,072 units in 3Q 2026.
Table 4: Vacancy Rate of Private Residential Properties by Quarter and Market Segment
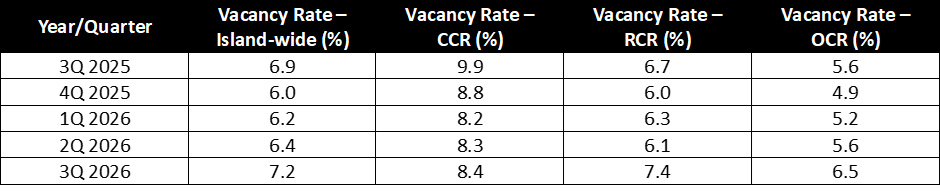
Amid the sharp uptick in completions, the vacancy rate for completed private residential properties (excluding ECs) also rose by 0.8 percentage points to 7.2% in 3Q 2026. Among market segments, the RCR saw the sharpest increase with its vacancy rate growing from 6.1% to 7.4%.
Table 5: Top 10 Non-Landed Private Projects Ranked by Rental Contracts
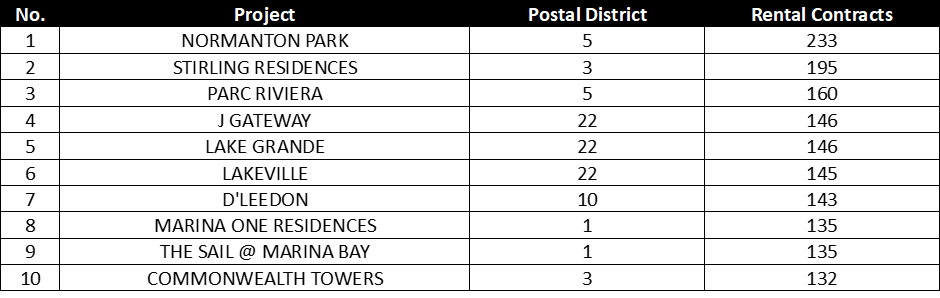
In 3Q 2026, Normanton Park saw the most rental activity with 233 contracts inked over the quarter. This was followed by Stirling Residences and Parc Riviera, which saw 195 and 160 rental contracts, respectively.
HDB Rental Market
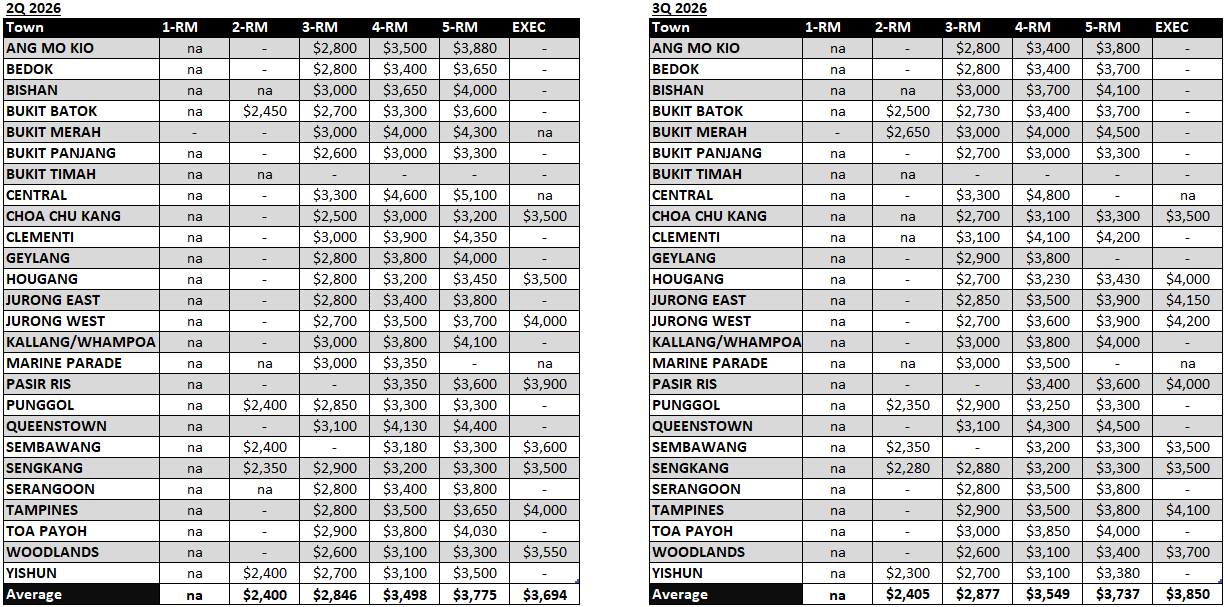
Table 6: HDB median rents by town and q-o-q growth
(na) Indicates that there are no rental transactions in the quarter
(-) Indicates that the median rent is not shown because there are fewer than 20 rental transactions in the quarter for that particular town and flat type
For 3Q 2026, executive flats in Hougang saw the sharpest gains in median rents, growing 14.3% q-o-q from $3,500 to $4,000. This was followed by 3-room flats in Choa Chu Kang, where median rents rose 8.0% q-o-q from $2,500 to $2,700. The third-highest increase was observed for 5-room flats in Jurong West with median rents rising 5.4% q-o-q from $3,200 to $3,300.
Chart 4: Number of rental approvals for HDBs
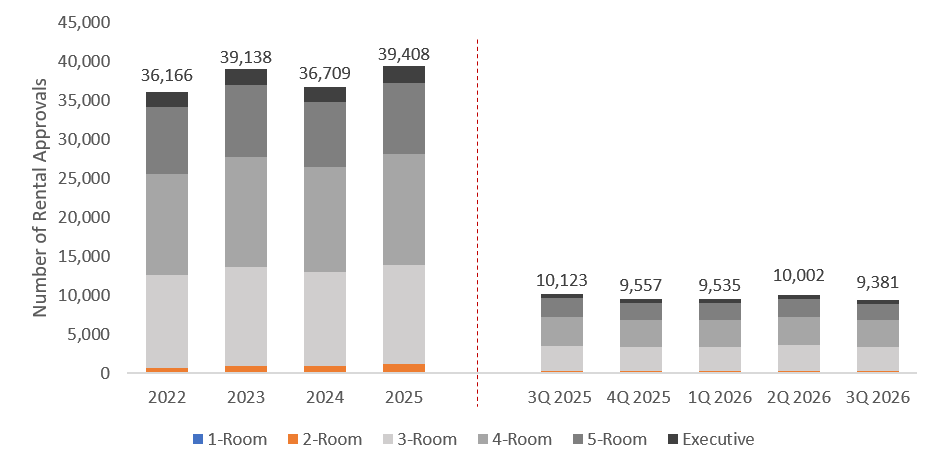
Rental applications for HDB flats fell 6.2% q-o-q to 9,381 approved cases. This brings the total number of approved HDB rentals for 9M 2026 to 28,918 cases. Four-room flats continued to account for the largest share of quarterly rentals, with 3,460 approved applications, followed by 3-room flats with 3,103 cases and 5-room flats with 2,069 cases.
Resilience expected for Singapore’s rental market in 2026
Despite a softening in HDB rental demand with fewer private property owners requiring interim housing after the 15-month wait-out period was lifted, overall residential leasing activity continued to hold up in 3Q 2026.
This leaves the private residential segment on track to meet ERA’s forecast of 88,000 to 93,000 rental transactions for the full year, accompanied by a 1% to 3% y-o-y increase in rents. Likewise, HDB rental volumes could remain on track to meet ERA’s forecast of 34,000 to 36,000 approved applications by end-2026, alongside a 2% to 5% y-o-y growth in median HDB rents.
However, as the year draws to a close and the festive season begins, leasing activity is expected to soften temporarily on seasonal factors. Overall rental volumes may therefore see some moderation in 4Q 2026, though the broader market outlook remains intact.